Flood Mapping and FEMA Certification
Your flood premium is set by one number. We measure it.
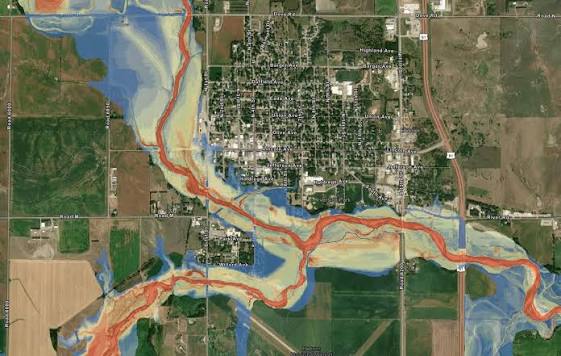
If your home sits in a FEMA-designated flood hazard zone, an Elevation Certificate is what tells your insurer how high you actually sit above the flood line — and whether you’re paying more than you should.
What the certificate actually measures
Flood zone & base flood elevation
Your parcel's designated zone and the water level FEMA expects in a 1%-annual-chance flood.
Geographic location
Latitude and longitude of the structure, tied to the official FEMA flood map.
Ground elevation at the foundation
Measured at each corner adjacent to the building, in feet above the datum.
Foundation & structure type
Slab, crawlspace, basement, or piers — how the building meets the ground.
Lowest storage level
The elevation of any crawlspace, basement, or below-grade area.
Lowest living area
The elevation your insurance rate is ultimately built around.
Mechanical equipment elevation
Furnace, water heater, and HVAC — equipment loss drives a large share of flood claims.
Photographs
Documents transferable rights above and beyond the parcel — foundational for lot line changes and development planning.
Do you actually need one?
You have a federally-backed mortgage
If you've recently purchased or refinanced a home in a flood hazard zone with a federally guaranteed mortgage, flood insurance — and the Elevation Certificate behind it — isn't optional. Most providers won't issue a policy without one.
You're insuring by choice
Anyone can buy flood coverage voluntarily. It's worth checking first: if your insurer already has a certificate on file for the property, it's most likely transferable, and you may not need a new survey at all.
Faulty FEMA maps have pushed some homeowners into paying for flood coverage they don’t need — a current, professionally surveyed certificate is often the only way to correct the record.
Read the report on TODAY.com →
How the survey happens
Give us the address
That's essentially all we need to start — the property address, and the name and contact information of whoever is authorizing the work and payment.
A licensed surveyor visits
We measure the ground, foundation, and floor elevations on site, in strict compliance with FEMA guidelines. Whether we need inside your home depends on your foundation type — see below.
Certificate in hand
Typically ready within one week to ten days. If your closing or renewal is urgent, tell us — we'll work to accommodate the timeline.
Will we need inside your house?
Foundation
Access required
Walkout basement
Usually not needed — measured from outside.
Slab foundation
Usually not needed — measured from outside.
Accessible crawlspace
Usually not needed — measured from outside.
Full basement
Access required — to record the basement floor elevation and enclosed square footage.
Not sure if you're in a flood zone?
Check the FEMA Map Service Center
Flood hazard zones are typically found in low-lying or coastal areas. FEMA has established a Base Flood Elevation for most of them — the water level with a 1% chance of being met or exceeded in any given year. Search your address on the FEMA Map Service Center, or call FEMA directly at (860) 448-0400.
Outside the New York area?
We serve the New York metro area directly — rivers, tributaries, and coastline alike. If your property is elsewhere, SurveySearch.net can connect you with a licensed surveyor experienced in your local flood maps.